WEG Large power transformers (10-350 MVA US; to 500 MVA Brazil)
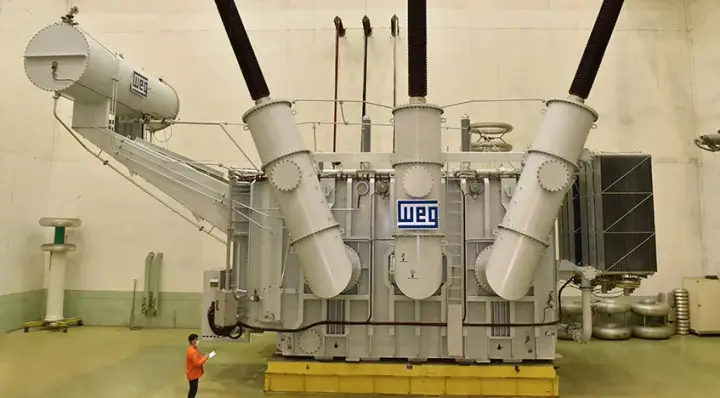
WEG large power transformers, 10-350 MVA US-built in Missouri with 525 kV single-phase proof in Brazil
This model is part of SecondWatt’s transformer research catalogue. Specifications and price observations are included where supported by sources. Equipment availability and commercial terms require confirmation.
WEG large power transformer dossier: 10-350 MVA US-built, HV to 400 kV, ester cooling classes, 77M USD expansion, market channels, inspection points.
WEG Transformers USA builds power transformers in Washington, Missouri, with substation units from 10 MVA base to 350 MVA top rating, high voltage 24.94-400 kV, low voltage to 230 kV, and 34.5 kV tertiaries, as GSU, autotransformer, and step-down types. Cooling spans ONAN, ONAN/ONAF, ODAF, and the ester classes KNAN and KNAN/KNAF, at 55, 55-65, or 65 C rise, to IEEE, CSA, and IEC standards; a pad-mount power line covers 10-20 MVA at up to 46 kV. Select units are manufactured in Mexico.
The Brazilian parent proves higher classes: three 500 MVA single-phase 440-to-525 kV units for TAESA's Assis substation (a 1.5 GVA bank) announced March 2026, 200-ton Itaipu units, and Brazil's first 525 kV underground transmission supply. A 77 million USD Washington, Missouri expansion broke ground September 2025 to lift US capacity.
No used WEG-brand large power unit was listed in US dealer inventories in August 2026, which ABB, GE, Westinghouse, and Waukesha nameplates dominate; the observed WEG secondary item is a never-energized 54/79/90 MVA 69 kV unit in trader stock, contact for pricing. Brazil-origin imports carry Section 232 derivative tariff exposure from 2025-08-18.
Why it matters
WEG is the scaling challenger among US power transformer makers: domestic Missouri production expanding 77 million USD, ester-cooling classes in the standard catalog, and 525 kV / 500 MVA capability proven at the parent. For buyers, a qualifying alternative vendor matters when incumbent queues run 120-210 weeks and imports carry 50% content tariffs.
Who buys it
Utilities, renewable developers, and industrial cogeneration projects buy WEG power units, with data center campuses meeting the brand at 69-345 kV interconnects. Gray-market buyers watch trader stock for cancellation units like the observed 90 MVA example, since used WEG supply has not yet formed.
Role in the data center
Campus interconnect and substation transformer at 69-345 kV, taking transmission or subtransmission service down to campus medium voltage. Its practical role in procurement is as an alternative vendor: qualifying WEG against an incumbent's order book is one of the few ways to move a delivery date in a market quoting up to four years at high capacity.
Key specifications
| US MVA range | 10-350 MVA |
|---|---|
| HV range | 24.94-400 kV |
| LV ceiling | 230 kV |
| Cooling classes | ONAN / ONAF / ODAF / KNAN / KNAF |
| Pad-mount power line | 10-20 MVA / to 46 kV |
| Brazil single-phase proof | 3x 500 MVA, 440-525 kV (TAESA) |
| US expansion | 77M USD Washington MO |
| Observed trader unit | 54/79/90 MVA, 69 kV, new-unused price on request |
| Duty types | GSU, autotransformer, step-down |
| Temperature rise options | 55 / 55-65 / 65 C |
| Tertiary winding | 34.5 kV available |
| Standards | IEEE, CSA, IEC |
| US manufacture | Washington, Missouri; select units from Mexico |
| Brazil 400 kV reference | 500 MVA / 400 kV units delivered ahead of schedule |
Technical summary
US substation units: 10-350 MVA. HV: 24.94-400 kV; LV to 230 kV; 34.5 kV tertiary. Types: GSU, autotransformer, step-down. Cooling: ONAN, ONAN/ONAF, ODAF, KNAN, KNAN/KNAF. Rise: 55 / 55-65 / 65 C. Standards: IEEE, CSA, IEC. Pad-mount power line: 10-20 MVA, to 46 kV. Brazil proof points: 500 MVA 1-phase at 525 kV (TAESA, 2026). Manufacture: Washington MO; select units from Mexico. US expansion: 77M USD Washington MO (groundbreaking Sept 2025).
Major variations
Duty splits three ways: generator step-up, autotransformer and step-down builds on a shared platform, with 34.5 kV tertiary windings available. Cooling and fluid combine into the second axis, with ONAN, ONAF and ODAF for mineral oil and KNAN and KNAF for ester fill, and rise options of 55, 55-65 and 65 C. Manufacturing origin is the third and drives tariff treatment: Washington, Missouri for US units, Mexico for select units, and Betim, Brazil for the largest designs. The pad-mount power line extends the family below 20 MVA at up to 46 kV.
Configurations and options
US-built substation units run 10 MVA base to 350 MVA top rating, with high voltage 24.94-400 kV, low voltage to 230 kV and a 34.5 kV tertiary available, as generator step-up, autotransformer or step-down types. Cooling is ordered as ONAN, ONAN/ONAF or ODAF for mineral oil, or KNAN and KNAN/KNAF for ester fill, at 55, 55-65 or 65 deg C rise, to IEEE, CSA or IEC. A pad-mount power line covers 10-20 MVA at up to 46 kV. Manufacturing origin is itself an option that moves both price and tariff treatment: Washington, Missouri for US units, Mexico for select units, and Betim, Brazil for the largest designs, where WEG built three 500 MVA single-phase 440 to 525 kV units for TAESA announced in March 2026. WEG publishes the 50-500 MVA envelope in its global catalog rather than on the US substation-units page.
Compatibility and dependencies
In campus and interconnect duty this unit takes transmission or subtransmission service at 24.94-400 kV down to a low-voltage winding at up to 230 kV. The tertiary is the option that cannot be added later: a 34.5 kV tertiary for station service or stabilizing duty has to be specified at order. Cooling class also reads as a fluid declaration, since KNAN and KNAN/KNAF identify an ester fill, which changes the fire separation case and moves the dissolved gas baseline off the mineral-oil limits in IEEE C57.104. Impedance has to be matched to the interrupting duty of the breakers downstream and BIL to the arrester scheme at the installed class. Cooling stages need station service for fans and pumps, and the rise class of 55, 55-65 or 65 deg C sets the overload headroom the operator can actually use. Transport at 10 MVA and above follows IEEE C57.150-2023.
Pricing and availability
Trend: rising Electrical Trader's price history, published 2026-04-01, puts power transformer prices up 77% between 2019 and 2026, driven by copper up roughly 70% and grain-oriented electrical steel up 80-100% from 2020 to 2025, together 50-55% of production cost. Wood Mackenzie figures reported by pv magazine USA on 2026-05-11 put substation transformer demand up 116% between 2019 and 2025. Terrapin Construction Group had substation lead times at 65-95 weeks for 5-25 MVA and 85-110 weeks for 25-50 MVA on 2026-06-10. Lead time, new: Quoted; class 120 weeks average, 80-210 weeks large. Lead time, used or refurbished: 2-12 weeks. Warranty, used: 3-year typical from major US rebuilders.
Lifecycle and maintenance
Liquid-filled transformers routinely serve 30-40 years with annual oil screening, DGA on a 1-2 year cadence (or continuous online monitoring on critical units), and gasket or bushing service as tests dictate. Major US rebuilders remanufacture units to like-new condition with warranties up to 3 years (T&R Electric, Sunbelt Solomon), and reconditioned stock ships in days against 65-210 week new-build queues. Remaining paper life, estimated by furan testing, governs end-of-life valuation.
Thermal and emissions profile
Transformers produce no combustion emissions; the regulatory profile is efficiency and fluid. US distribution-class units fall under DOE 10 CFR 431 Subpart K efficiency standards, amended in 2024 with compliance from 2029 requiring 10-30% lower losses than 2016 levels. Fluid choice drives fire and environmental posture: mineral oil versus FR3 natural ester with a 360 C fire point and ready biodegradability. Legacy units require PCB screening, with clean units documented below 2 ppm.
Common failure points
- Windings — Dielectric failure; windings dominate major-failure statistics in CIGRE TB 642
- Bushings — Failure share rises with voltage class; OIP bushing faults can rupture tanks
- OLTC — Contact and mechanism wear; prominent failure source on substation units
- Winding deformation — Through-fault or transport damage shifting SFRA signature
- Cooling system — Pump, fan, and radiator degradation derating the unit
- Moisture and paper aging — Furans in oil and reduced degree of polymerization
Inspection checklist
DGA: dissolved gas analysis per IEEE C57.104; combustible-gas trend rise between 2 samples triggers investigation. Oil quality: dielectric breakdown, moisture, acidity, and furan tests; degree of polymerization below 200 marks end of paper life. Insulation resistance: megger HV/LV/ground; polarization index of 2.0 or higher passes. Power factor: insulation power factor testing; values above 1.0% on oil-filled windings warrant investigation. Turns ratio: TTR on all taps; deviation beyond 0.5% from nameplate fails. Winding resistance: three-phase balance within 2% between phases. Bushings: capacitance and power factor test; bushing failure share rises with voltage class per CIGRE TB 642. OLTC: inspect on-load tap changer diverter and selector; OLTCs are a leading failure component in CIGRE TB 642 fleet surveys.
Procurement channels
WEG US sales for new units from Washington, Missouri, quoted per project. Never-energized surplus appears in trader stock, with a 54/79/90 MVA 69 kV unit at Transformer Traders in August 2026, contact for pricing. No used WEG large power channel has formed, because US output is recent; dealer inventories in this class are dominated by ABB, GE, Westinghouse and Waukesha nameplates, and those are the realistic used comparables.
Regional notes
Brazil-origin units are exposed to Section 232 50% derivative tariffs from 2025-08-18; Washington MO production is exempt. WEG's own announcement states five North American transformer factories without listing each location.